
 Gibraltar Federation of Small Businesses


 Gibraltar Federation of Small Businesses


New rules give eligible retailers and wholesalers a route to tax relief on some of the additional Transaction Tax incurred during the first 90 days of Treaty implementation. The detail is important, including who qualifies, how the deduction is calculated and the choice businesses will need to make between this measure and forthcoming modernisation support.
Government has now published the Transaction Tax (Deductions) Rules 2026, putting one of the business-support measures announced in this year’s Budget onto a statutory footing.
The rules target eligible retail and wholesale businesses that have paid more under Transaction Tax than they would previously have paid under Gibraltar’s Import Duty regime during the first 90 days following provisional Treaty implementation on 15 July. (Gibraltar Government). For qualifying businesses, the measure provides a deduction against assessable profits equal to the difference between the Transaction Tax paid and the Import Duty that would otherwise have applied, where Transaction Tax is higher.
That makes this an income-tax relief mechanism, with the qualifying amount feeding into the business’s taxable-profit calculation.
The scheme:
The initial 90-day period can also be extended in further 90-day blocks on the advice of an independent committee appointed by the Minister. (Gibraltar Government)
The relief is aimed specifically at retailers and wholesalers affected by the transition from Import Duty to Transaction Tax. Businesses need to obtain Office of Fair Trading certification to support a claim. Several categories are excluded where their principal business involves selling:
That means eligibility depends on the nature of the business as well as the tax paid. Businesses with more varied product ranges may therefore want to establish early how their principal activity is treated for certification purposes rather than assume eligibility from individual transactions.
The starting point is the additional tax burden created by the change in regime. Where the Transaction Tax paid on qualifying imports during the relevant period exceeds the Import Duty that would previously have applied, the difference can form the basis of the deduction.
There is a further limit. The deduction is capped at 50% of the tax paid in the preceding accounting period or year of assessment, and is applied to the first accounting period or year of assessment beginning on or after 15 July 2026.
Businesses therefore need more than their Transaction Tax records. Their previous tax position also determines the maximum amount of relief available.
For retailers and wholesalers considering a claim, this is likely to require coordination between whoever manages imports and customs documentation and whoever handles the company’s tax affairs.
Although the rules were published on 23 September, the qualifying period begins from 15 July, when the Treaty arrangements were provisionally applied. Eligible businesses can therefore include qualifying Transaction Tax already incurred since implementation began, as well as tax paid through the remainder of the initial 90-day period ending on 12 October.
That gives businesses a relatively short window to assemble the information required while the qualifying period is still running. Government has specifically encouraged businesses to retain full records of Transaction Tax paid and begin the OFT certification process.
The rules also connect the relief to wider business compliance.
Businesses must have been compliant with their tax, PAYE and social insurance obligations on 15 July 2026, or become compliant within 30 days of the rules coming into force with written approval from the Commissioner of Income Tax. Claims must include both OFT certification and evidence of the Transaction Tax paid. For businesses considering the deduction, it makes sense to review the wider compliance position at the same time as the customs and accounting records.
Another business-support measure is still to come. Government says it will shortly publish a separate modernisation scheme covering investment in areas including premises, processes, IT and staff training. (Gibraltar Government)
Businesses will be able to benefit from one of the two measures. A company receiving relief under the Transaction Tax (Deductions) Rules will not also qualify for support under the modernisation scheme. (Gibraltar Government)
That introduces a commercial decision for businesses that could potentially access both.
For some, relief against the increased Transaction Tax burden may offer the stronger benefit. Others planning technology, premises or workforce investment may want to understand the modernisation scheme before deciding which route provides greater value.
The Government has not yet published the detailed terms of that second scheme, so businesses should avoid making assumptions about its eventual value or eligibility criteria until those rules are available.
For potentially eligible retailers and wholesalers, there are several practical steps worth taking before 12 October.
First, identify the Transaction Tax paid since 15 July and establish what Import Duty would previously have applied to those goods. Then review the prior accounting period’s tax payment so the 50% cap can be understood.
Businesses should also check their tax, PAYE and social insurance position and begin the Office of Fair Trading certification process. Finally, the forthcoming modernisation scheme needs to remain part of the decision. Businesses considering investment in technology, premises, processes or staff development may want to compare the two forms of support once the second scheme is published.
The deduction rules provide the first detailed route for businesses to access one of the Treaty-related support measures announced earlier this year. The immediate task is to establish eligibility, quantify the potential relief and decide whether this is the right support route for the business.
Minister Arias-Vasquez Publishes Transaction Tax (Deductions) Rules 2026
https://www.gibraltar.gov.gi/press-releases/minister-arias-vasquez-publishes-transaction-tax-deductions-rules-2026-6922026-12358
Transaction Tax (Deductions) Rules 2026, Legal Notice 2026/338
https://www.gibraltarlaws.gov.gi/


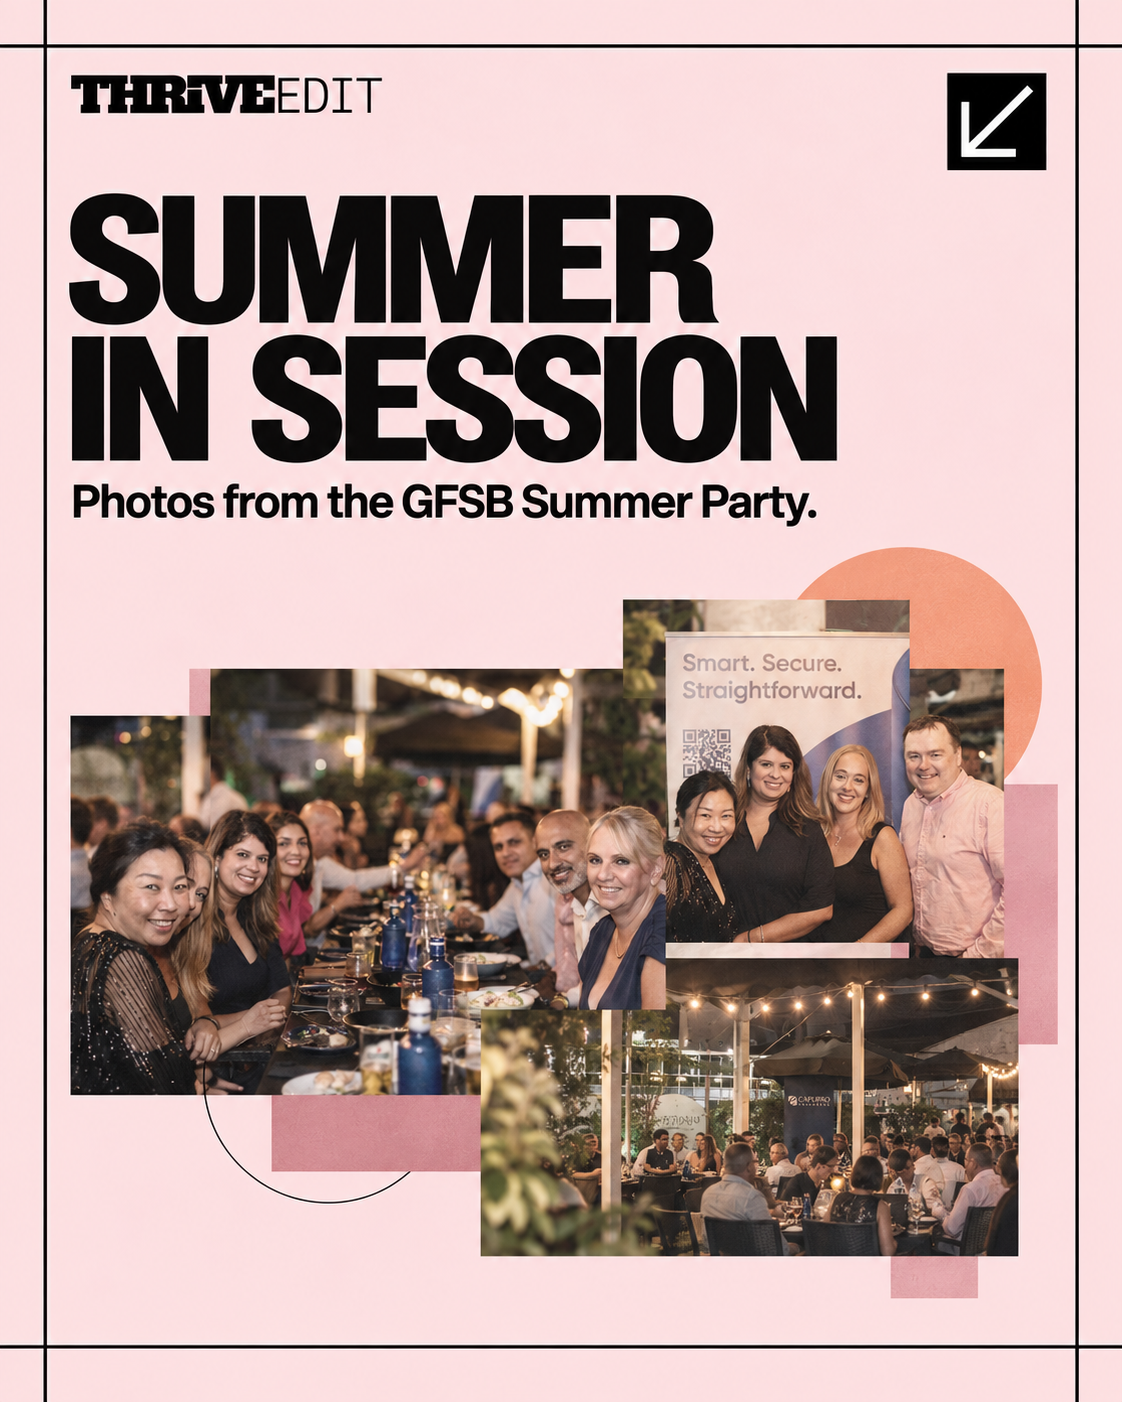

Last week’s GFSB Summer Party brought members together for an evening of conversation, new connections and a chance to reconnect ahead of Q4. With thanks to justbank and Capurro Insurance for supporting the event, we’ve pulled together some of our favourite photos from the night.
Gibraltar still has an advantage at the pump, but higher global diesel costs are feeding into freight, logistics and imported goods.
Toby White explains Know Your Agent, agentic commerce and how businesses can prepare as AI assistants begin booking, buying and acting for customers.
Nutritional coach and therapist MJ Feeke shares practical ways to support steadier energy, concentration and mood through a busy working day.
Europe’s SMEs are calling for growth, investment and proportionate regulation. We look at the lessons from SME2B Business Forum Europe for Gibraltar businesses.